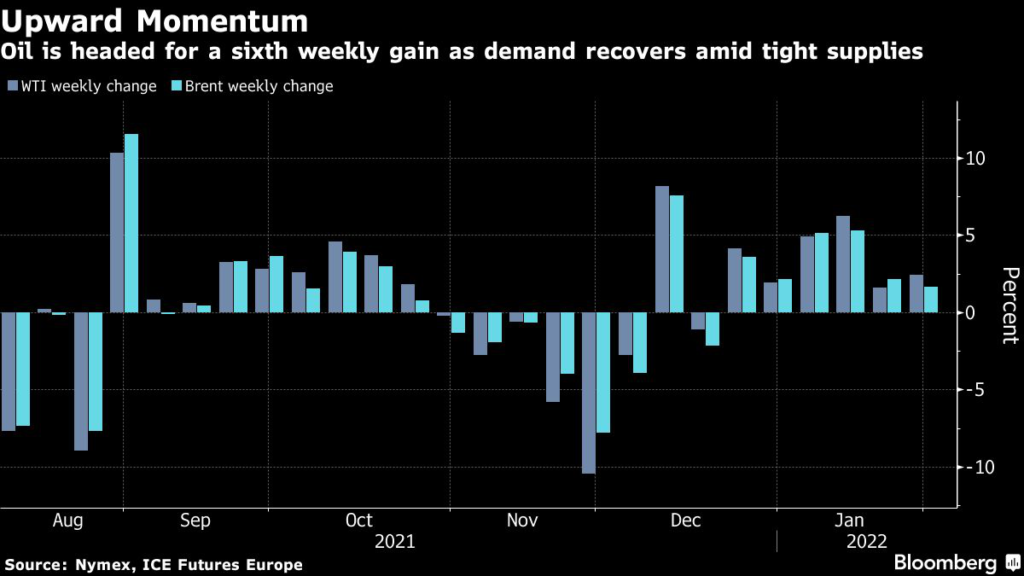
(Bloomberg) — Oil is headed for a sixth straight weekly gain, with prices trading near a seven-year high as crude makes a roaring start to 2022.
West Texas Intermediate rose above $88 a barrel, taking its advance this week to more than 3%, while the global Brent benchmark approached $91 as robust demand tightened global markets. Heightened geopolitical risks driven by fears that Russia may invade Ukraine have also contributed to crude’s climb.
Oil’s stellar run comes despite a soft patch in global equity markets after the Federal Reserve signaled it’s ready to tackle inflation. For now, crude prices have defied the pull of weaker risk sentiment elsewhere, with consumption on the brink of returning to pre-pandemic levels.
See more: Diesel Margins Surge Around the World in Constrained Market
Attention will shift next week to the Organization of Petroleum Exporting Countries and its allies as they meet Feb. 2 to assess the market and decide on supplies for March. While OPEC+ has been steadily easing output curbs, there’s concern members have been unable to deliver the promised volumes in full.
“Wider market supply/demand fundamentals remain tight,” said Ashley Kelty, a senior analyst at Panmure Gordon. “Investor focus will remain on the situation in Europe, with one eye kept on any proclamations from OPEC+ energy ministers” ahead of next week’s meeting.
In a sign of the market’s strength, prices remain heavily backwardated — a bullish pattern whereby near-term contracts trade above those further out — indicating tight immediate supply. Brent’s prompt timespread was at $1.34 a barrel in backwardation on Friday, up from 41 cents at the start of the month.
As crude advances, key product prices have been dragged higher. Wholesale gasoline in the New York market has surged to the highest seasonal level in three decades of record-keeping. Average pump prices across the U.S. are headed for a monthly gain after jumping 46% last year.
More stories like this are available on bloomberg.com
©2022 Bloomberg L.P.