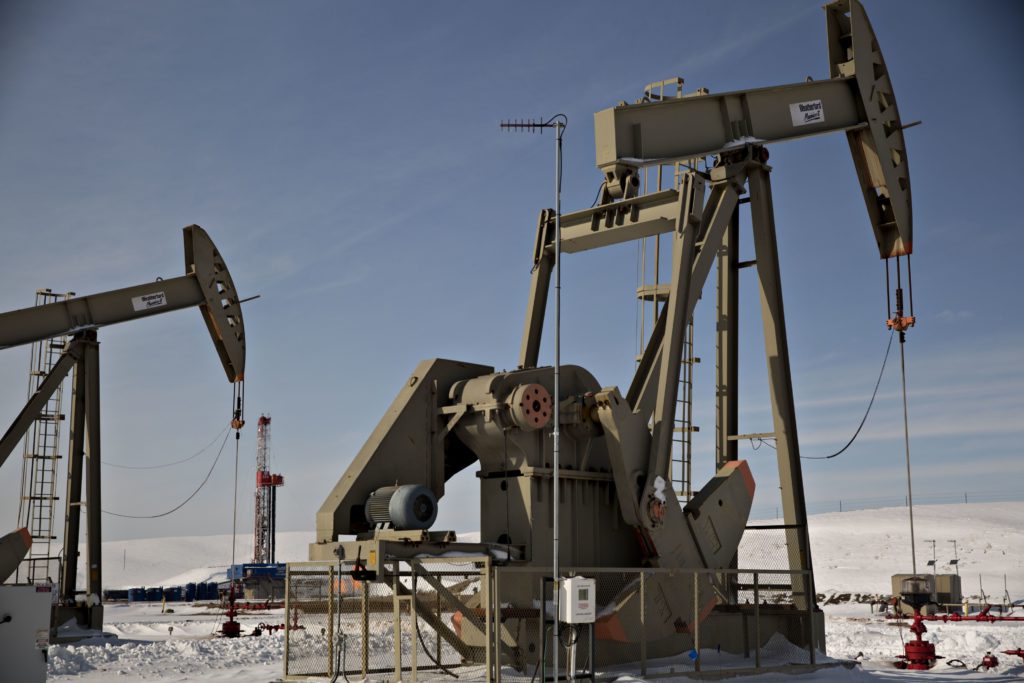
(Bloomberg) — Oil fell for a second day as a red-hot start to the week fizzled, with the market reassessing the potential demand hit from omicron.
Futures in New York edged toward $70 a barrel after sliding 2% on Thursday with other financial assets. Oil demand has so far escaped a major blow from the new strain of the virus, although some nations have started implementing renewed restrictions. A study has found that omicron is 4.2 more times transmissible than the delta variant in its early stages.
Crude is still set for the biggest weekly gain since August after jumping more than 9% during the first three days of the week. It’s a remarkable turnaround after oil tumbled into a bear market following a multi-week plunge.
There are other bearish signs mounting. Traders are facing the prospect of a weakening physical market for crude in Asia, despite Saudi Arabia’s move to increase oil prices for January. The prompt timespread for global benchmark Brent has also narrowed and is inching toward a bearish contango structure — where near-dated contracts are cheaper than later ones.
See also: Oil’s Omicron Optimism Isn’t Showing Up in Key Spread: Chart
“Fears surrounding omicron have somewhat receded but the broad declines overnight show it’s not truly over,” said Howie Lee, an economist at Oversea-Chinese Banking Corp. in Singapore. “For now, we see Brent trading between $70-$75, but if omicron proves less of a threat than initially expected, then I see Brent returning back above $80 in the new year.”
Many parts of the eastern U.S., including New Jersey and Connecticut, are seeing a rise in hospitalizations. The City of London could also be about to become a ghost town again after firms started telling thousands of staff to work from home in response to the latest U.K. government guidance.
More stories like this are available on bloomberg.com
©2021 Bloomberg L.P.