(Bloomberg) — U.S. equity futures climbed with European stocks Wednesday as investors awaited a key Federal Reserve decision and assessed a slew of earnings reports.
Contracts on U.S. gauges also climbed, with a jump of more than 2% in Nasdaq 100 futures signaling a rebound for tech shares. Microsoft Corp. and Texas Instruments Inc. gained in premarket trading after delivering upbeat outlooks. AT&T Inc. and Boeing Co. also gained after results.
Europe’s Stoxx 600 benchmark also rose more than 2%, buoyed by rallies in energy and travel shares.
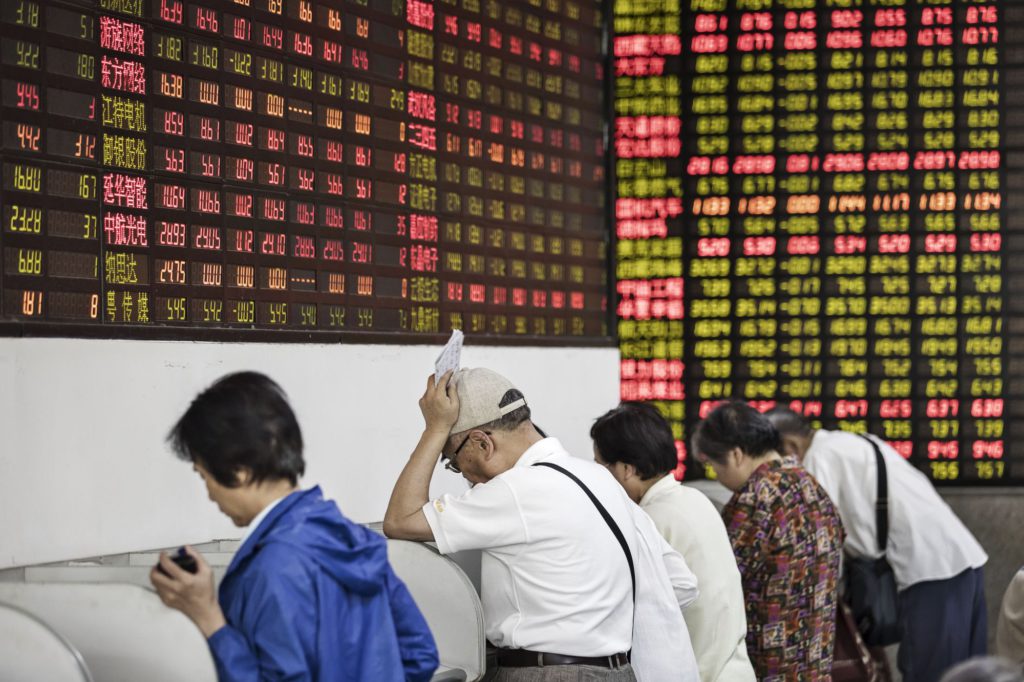
Markets have been volatile going into the Fed decision, with Russia-U.S. tension adding to investor concerns. Traders are waiting to see how hawkish the central bank sounds in its fight to tame inflation — both over interest-rate hikes expected from March and subsequent reductions in its holdings of Treasuries.
Still, there are some signs of easing turmoil. The Cboe Volatility Index known as the VIX fell from a one-year high, snapping six days of gains.
The benchmark U.S. 10-year Treasury yield ticked up, while a dollar gauge was little changed.
“We expect inflation to remain high and interest rates to rise more than investors are expecting today,” said Norbert Frey, head of portfolio management at Fuerst Fugger Privatbank. “A rising interest rate environment is leading to a revaluation of all business models and we think 2022 can be a year of value stocks.”
Global stocks have shed about 7% in January, on track for the worst month since the pandemic roiled markets back in 2020. Some strategists are optimistic about the outlook following the declines.
Goldman, Citi Strategists Say It’s Now Time to Buy Stocks Rout
“Starts of policy normalisation typically bring higher volatility but rarely terminate bull markets, although higher-than-usual P/E multiples mean equities are more rates-sensitive this time,” Emmanuel Cau, head of European equity strategy at Barclays Plc, wrote in a note.
Meanwhile, Bitcoin extended its gains for the week, trading near $38,000. Crude climbed, with Brent heading toward $90 a barrel, after industry estimates showed a draw in U.S. stockpiles and investors tracked tensions over Ukraine for signs the conflict may disrupt supplies.
U.S. President Joe Biden said he would consider personally sanctioning Vladimir Putin if he orders an invasion of Ukraine, escalating efforts to deter the Russian leader from war.
Elsewhere, a gauge of Asia-Pacific shares treaded lower.
Here are some more views about the Fed:
- “For the Fed, the current risk-asset drawdown certainly makes their job more difficult, but we don’t see the level of financial conditions tightening as commensurate with a dovish message,” Ed Acton, a strategist at Citigroup Inc., wrote in a note. “Instead, the FOMC may seek to underline the current inflation risks as a ‘constraint’ on monetary policy going forward.”
- “They could end QE a month earlier” in February versus March, Kelsey Berro, fixed-income portfolio manager at JPMorgan Asset Management, said on Bloomberg Television, referring to quantitative easing. “That would just reinforce the fact that we expect the first rate hike in March and then quarterly rate hikes after that.”
- “A moderately hawkish Powell would be dovish in market terms,” Steven Englander, global head of G-10 FX research at Standard Chartered Bank, wrote in a note. “If Powell says that the FOMC is committed to getting inflation on track and still hopeful that a couple of hikes combined with some QT will be enough, that is dovish by market pricing,” he said, referring to quantitative tightening.
What to watch this week:
- Fed, Bank of Canada monetary policy decisions Wednesday.
- EIA crude oil inventory report Wednesday.
- U.S. new home sales, wholesale inventories Wednesday.
- South African Reserve Bank rate decision Thursday.
- U.S. initial jobless claims, durable goods, GDP Thursday.
- Euro zone economic confidence, consumer confidence Friday.
- U.S. consumer income, University of Michigan consumer sentiment Friday.
For more market analysis, read our MLIV blog.
Some of the main moves in markets:
Stocks
- Futures on the S&P 500 rose 1.5% as of 8:17 a.m. New York time
- Futures on the Nasdaq 100 rose 2.3%
- Futures on the Dow Jones Industrial Average rose 1.1%
- The Stoxx Europe 600 rose 2.2%
- The MSCI World index rose 0.4%
Currencies
- The Bloomberg Dollar Spot Index was little changed
- The euro fell 0.2% to $1.1278
- The British pound was little changed at $1.3513
- The Japanese yen fell 0.4% to 114.28 per dollar
Bonds
- The yield on 10-year Treasuries advanced one basis point to 1.78%
- Germany’s 10-year yield advanced one basis point to -0.07%
- Britain’s 10-year yield advanced three basis points to 1.20%
Commodities
- West Texas Intermediate crude rose 1.5% to $86.91 a barrel
- Gold futures fell 0.3% to $1,849 an ounce
More stories like this are available on bloomberg.com
©2022 Bloomberg L.P.