(Bloomberg) — U.S. equity futures rebounded Wednesday after another volatile Wall Street session ahead of a Federal Reserve policy decision that’s expected to signal a March interest-rate liftoff.
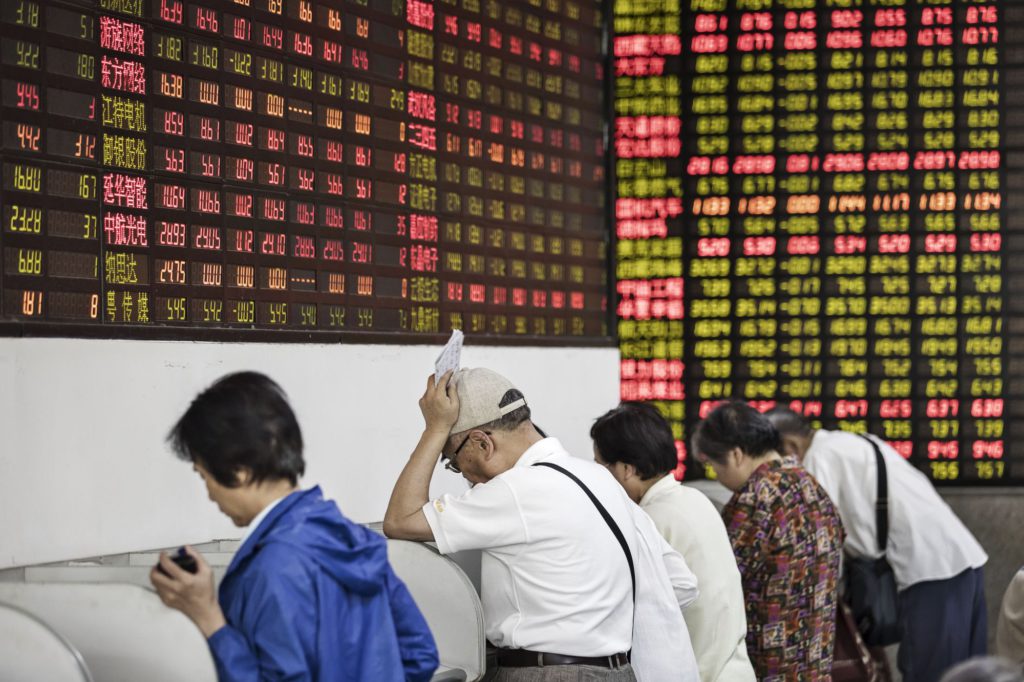
U.S. contracts initially dropped early in Asia before turning higher. Futures were steady for Japan and higher for Hong Kong. The S&P 500 erased a near-3% intraday slide Tuesday but subsequently fell again to close at the lowest since October, while the technology-heavy Nasdaq 100 underperformed.
Microsoft Corp. stoked worries about the tech outlook. The firm’s shares and the Invesco QQQ Trust Series 1 — an ETF that tracks the Nasdaq 100 — slid in extended trading after Microsoft reported slowing cloud-services revenue.
The benchmark U.S. 10-year Treasury yield was little changed ahead of the Fed, while the dollar was mixed against major peers. Crude oil held a rally, in part on the risk that a Russia-Ukraine conflict could disrupt supplies.
Traders are waiting to see how hawkish the Fed sounds in the fight against high inflation, both over rate hikes and reducing its holdings of Treasuries. The prospect of receding stimulus as the economic rebound from the pandemic notches down a gear could be a recipe for more market swings. Global stocks are already down over 7% this year.
While the Fed could spur more selling if they flex hawkish, Chair Jerome Powell will likely say policy is data-dependent and supply chains are improving, while indicating that inflation could be peaking, Frances Stacy, portfolio strategist at Optimal Capital, said on Bloomberg Television.
“I think what that’s going to do is potentially reassure markets that the Fed put is ready, willing and able,” she said. “That could cause some serious enthusiasm and a short squeeze.”
Goldman Sachs Group Inc. strategists warned that the risk of a “growth shock” to equities is increasing. The International Monetary Fund cut its global economic expansion forecast for 2022, citing weaker prospects for the U.S. and China along with persistent inflation.
What to watch this week:
- Fed monetary policy decision Wednesday.
- EIA crude oil inventory report Wednesday.
- U.S. new home sales, wholesale inventories Wednesday.
- South African Reserve Bank rate decision Thursday.
- U.S. initial jobless claims, durable goods, GDP Thursday.
- Euro zone economic confidence, consumer confidence Friday.
- U.S. consumer income, University of Michigan consumer sentiment Friday.
For more market analysis, read our MLIV blog.
Some of the main moves in markets:
Stocks
- S&P 500 futures were steady as of 8:34 a.m. in Tokyo. The S&P 500 fell 1.2%
- Nasdaq 100 futures climbed 0.3%. The Nasdaq 100 fell 2.5%
- Nikkei 225 futures were steady
- Hang Seng futures advanced 0.6% earlier
Currencies
- The Bloomberg Dollar Spot Index was little changed
- The euro was at $1.1302
- The Japanese yen was at 113.91 per dollar
- The offshore yuan was at 6.3311 per dollar
Bonds
- The yield on 10-year U.S. Treasuries was at 1.77%
Commodities
- West Texas Intermediate crude fell 0.3% to $85.32 a barrel
- Gold was at $1,849.37 an ounce
More stories like this are available on bloomberg.com
©2022 Bloomberg L.P.