(Bloomberg) — Equities in Europe declined on Monday and U.S. futures reversed gains as the rout in technology stocks deepened amid concerns over the Federal Reserve’s imminent rate liftoff. Bonds gained.
Tech stocks were among the largest decliners as the Stoxx Europe 600 index dropped almost 2%, on track for the biggest two-day slump since October. Tensions between Russia and Ukraine exacerbated the risk-off mood, with Russia’s benchmark stock index tumbling as much as 4.4% and European shares with exposure to the region also under pressure.
U.S. equity futures edged lower, dimming hopes of some respite after one of the worst stretches for global shares last week since the pandemic began. Contracts on the tech-heavy Nasdaq 100 turned lower after climbing as much as 1% earlier. The Treasury 10-year yield dipped along with rates on most European bonds. A dollar gauge ticked higher.
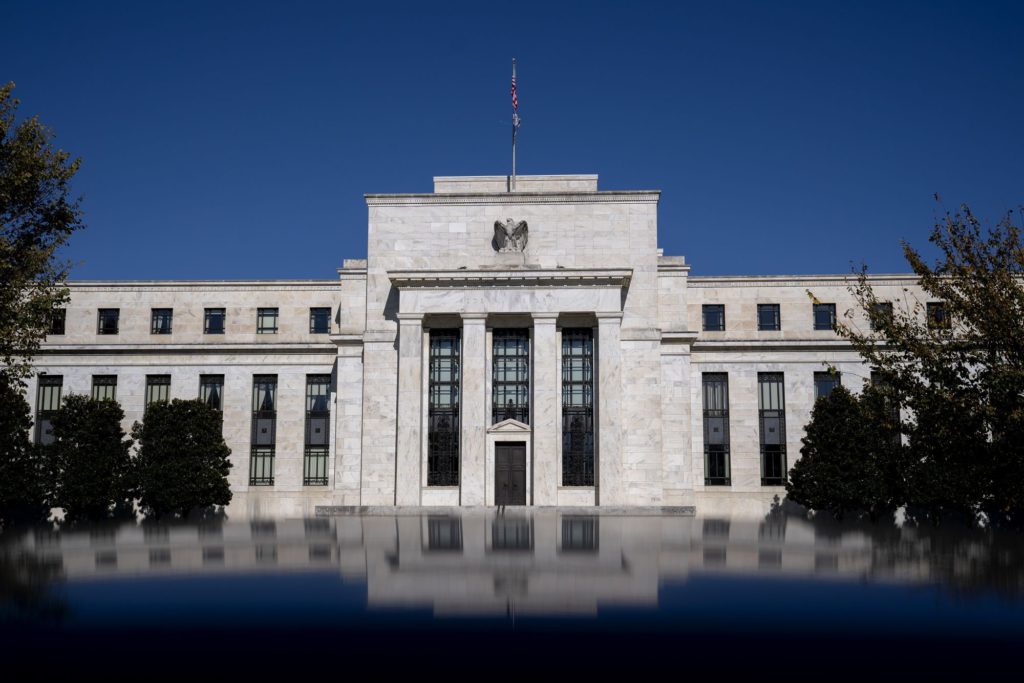
The Fed on Wednesday is expected to signal a March hike in interest rates and balance-sheet reduction later this year to help fight inflation. Ebbing stimulus is forcing a rethink about the economic and market outlook.
Aside from the Fed and Ukraine, earnings updates from titans such as Apple Inc. will shape sentiment too in the days to come following an uneven start to the reporting season. Tech stocks have borne the brunt of an equity selloff this year, while some less richly valued parts of the market have held up better.
There is “likely a longer term rotation toward value stocks measured in quarters, not weeks” unfolding, Julian Emanuel, chief equity and quantitative strategist at Evercore ISI, wrote in a note. “Investors should retain a balanced view, staying patient in committing new capital to equities.”
Goldman Sachs Group Inc. economists said they see a risk the Fed will tighten monetary policy more aggressively this year than the Wall Street bank now anticipates.
Speculators in Retreat
“A March lift-off and four hikes in 2022 are already fully priced in,” said Xavier Chapard, global macro strategist at Credit Agricole CIB. “But we expect Chair Powell to remain hawkish and not offer any pushback. Not supportive for risky assets.”
In the volatile cryptocurrency sector, bruised Bitcoin fell below $34,000, extending a plunge over the past three days. Digital coins have shed more than $1 trillion in value since a November high.
For more market analysis, read our MLIV blog.
What to watch this week:
- Earnings reports are due from companies including Apple, Boeing, GE, 3M, Deutsche Bank, Microsoft, Samsung Electronics and Tesla
- PMIs for Eurozone, France, Germany, U.K. and Australia, Monday
- Australia CPI, Tuesday
- Federal Reserve rate decision and Chair Jerome Powell news conference, Wednesday
- Bank of Canada interest-rate decision, Wednesday
- EIA crude oil inventory report, Wednesday
- U.S. fourth-quarter GDP growth data, plus U.S. initial jobless claims and durable goods, Thursday
- U.S. consumer income, University of Michigan consumer sentiment figures, Friday
Some of the main moves in markets:
Stocks
- The Stoxx Europe 600 fell 1.8% as of 10:17 a.m. London time
- Futures on the S&P 500 fell 0.1%
- Futures on the Nasdaq 100 fell 0.2%
- Futures on the Dow Jones Industrial Average were little changed
- The MSCI Asia Pacific Index fell 0.7%
- The MSCI Emerging Markets Index fell 1.4%
Currencies
- The Bloomberg Dollar Spot Index rose 0.2%
- The euro fell 0.2% to $1.1323
- The Japanese yen rose 0.1% to 113.54 per dollar
- The offshore yuan rose 0.2% to 6.3284 per dollar
- The British pound fell 0.3% to $1.3512
Bonds
- The yield on 10-year Treasuries declined four basis points to 1.72%
- Germany’s 10-year yield declined three basis points to -0.10%
- Britain’s 10-year yield declined four basis points to 1.13%
Commodities
- Brent crude rose 0.3% to $88.15 a barrel
- Spot gold rose 0.3% to $1,841.76 an ounce
More stories like this are available on bloomberg.com
©2022 Bloomberg L.P.