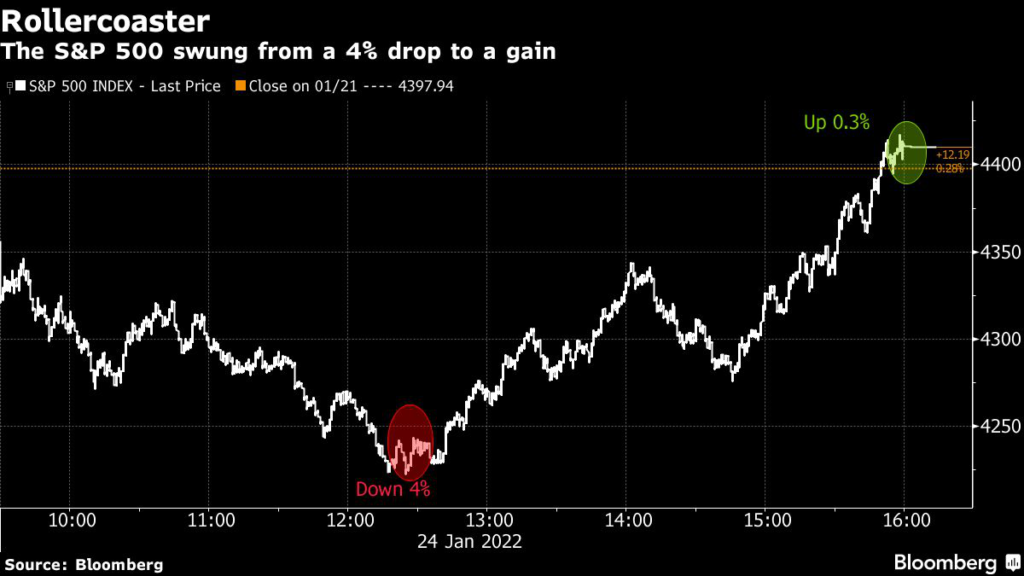
(Bloomberg) — Asian stocks looked set for a choppy start Tuesday after U.S. shares wiped out a 4% rout to close higher in a wild session roiled by concerns over Federal Reserve policy tightening and geopolitical tension.
Futures for Japan, Australia and Hong Kong pointed lower earlier. Dip buyers left the S&P 500 and Nasdaq 100 in the green amid high volumes, a breathtaking turnaround of a U.S. selloff that at one point rivaled any of the last two years.
Treasuries were mixed and the yield curve steepened. An auction of two-year notes attracted the strongest demand since February 2020. Oil slid in New York.
The prospect of a Fed interest-rate hiking cycle and balance-sheet reduction to tackle inflation is rattling markets. Escalating U.S.-Russia tension over Ukraine has also encouraged demand for havens. A gauge of the dollar rose.
Global shares are on course for their worst month since the pandemic began on risks from ebbing Fed stimulus as well as an uneven start to the company earnings season. The question now is whether the slide is a buying opportunity or portends wider stress across more asset classes.
“Volatility is back,” Lori Calvasina, head of U.S. equity strategy at RBC Capital Markets, said on Bloomberg Television. “We’re having a sea-change in terms of Fed policy. Equity investors frankly have been behind the curve in anticipating what’s coming, so there’s a lot of catch-up to do.”
The Cboe Volatility Index, a gauge of implied equity swings for the S&P 500, at one point Monday spiked to the highest level in over a year before receding. The Russell 2000 gauge of U.S. small-caps lifted from bear market levels to end more than 2% up.
Rocky Time
A team of Oppenheimer strategists led by John Stoltzfus wrote Monday that the stock recovery may come sooner than expected and “it’s time to make shopping lists and look for ‘babies that got thrown out with the bath water.’”
But Jeremy Siegel, a professor at the Wharton School of the University of Pennsylvania and author of “Stocks for the Long Run,” said investors should brace for challenges this quarter.
“I’m still very positive on long-term equities but I think it’s in for a rocky time the next two or three months,” he said. “We have to get used to the fact that the Fed is going to be much more hawkish.”
In the latest development over Ukraine, where Russian troops are massing on the nation’s borders, the U.S. is putting as many as 8,500 troops on heightened alert for deployment to bolster NATO forces in Eastern Europe if needed. Russia has denied it intends to invade.
In cryptocurrencies, Bitcoin — a poster child for swings in sentiment — climbed Monday for the first time in six days.
Elsewhere, China Evergrande Group urged offshore bondholders not to adopt aggressive legal action over repayments, after an ad-hoc group of its overseas creditors threatened to take enforcement measures.
For more market analysis, read our MLIV blog.
What to watch this week:
- IMF launches the World Economic Outlook update Tuesday.
- U.S. Conference Board consumer confidence Tuesday.
- Fed monetary policy decision Wednesday.
- EIA crude oil inventory report Wednesday.
- U.S. new home sales, wholesale inventories Wednesday.
- South African Reserve Bank rate decision Thursday.
- U.S. initial jobless claims, durable goods, GDP Thursday.
- Eurozone economic confidence, consumer confidence Friday.
- U.S. consumer income, University of Michigan consumer sentiment Friday.
Some of the main moves in markets:
Stocks
- The S&P 500 rose 0.3%
- The Nasdaq 100 rose 0.5%
- Nikkei 225 futures fell 0.9%
- S&P/ASX 200 futures retreated 1.3%
- Hang Seng futures declined 1.9%
Currencies
- The Bloomberg Dollar Spot Index rose 0.3%
- The euro was at $1.1325
- The Japanese yen was at 113.96 per dollar
- The offshore yuan was at 6.3331 per dollar
Bonds
- The yield on 10-year Treasuries rose one basis point to 1.77%
- Australia’s 10-year yield was at 1.94%
Commodities
- West Texas Intermediate crude fell 2.2% to $83.31 a barrel
- Gold was at $1,843.15 an ounce
More stories like this are available on bloomberg.com
©2022 Bloomberg L.P.